


U.S. millwork sectoral output fell to $30.74 billion in 2023, down 12.1% from the $34.98 billion peak in 2022.[1] Private construction put in place hit $1.652 trillion in 2025, down 2.6% from the prior year, with single-family housing down 3.4% and multi-family down 9.1%.[2] Only one category grew: residential improvements, up 1.2%.[2]
That is the backdrop for every equipment decision a shop will make this year. But the headline trend is not the slowdown, it is the split. Shops that grew sales in 2025 plan to keep investing. Shops that lost sales plan to wait. What follows, drawn from federal statistics and peer-reviewed research, shows what that split actually means for your next machine purchase.
Capital Investment Contracted, But the Buyers Still Buying Are Pulling Ahead
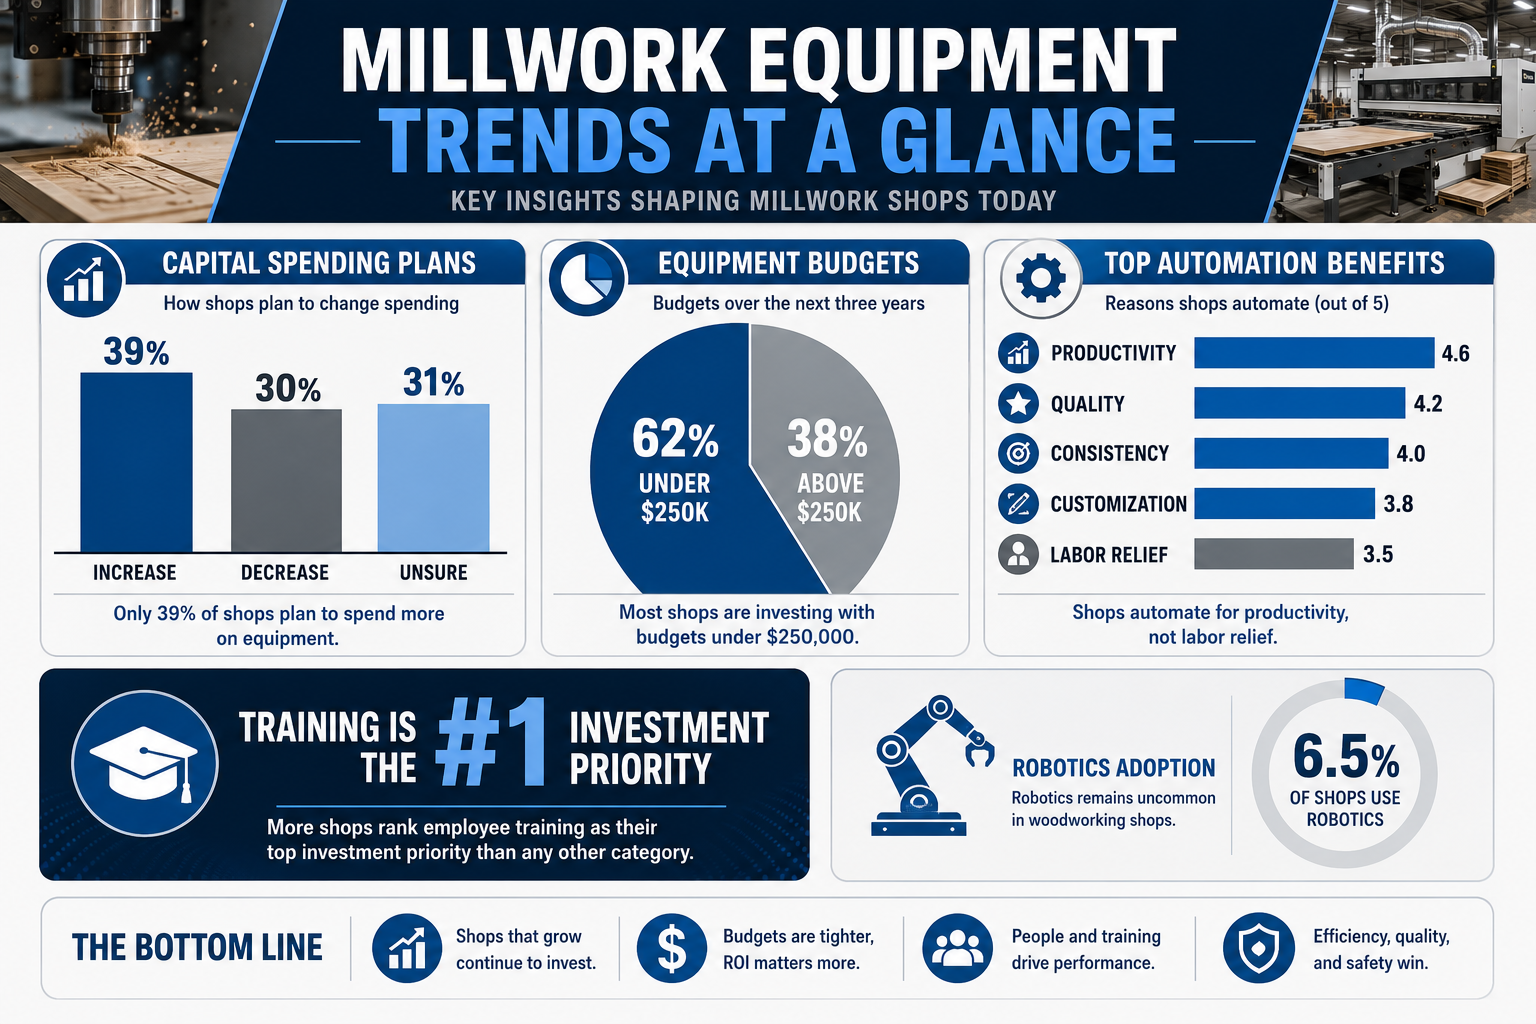
Only 39% of secondary woodworking manufacturers planned to spend more on productivity and capability in 2026 than they did in 2025.[2] Two years earlier, that number was 49%.[3] Investment appetite dropped ten points.
Sales explain most of it. In 2025, 48% of manufacturers reported worse sales volume, up from 30% the year before.[2] But the split within that number matters more than the average. Among firms that grew sales volume in 2025, 53% planned to increase investment in 2026. Among firms that lost volume, just 28% planned to increase.[2]
The shops continuing to invest are not ignoring the market, they are reading it differently. Browse CNC machining centers and edgebanders to see what the active buyers are choosing right now.
The 2026 Buyer: Small Shop, Focused Budget
Most equipment coverage targets a buyer who does not exist in volume. The real 2026 buyer runs a small shop with a tight budget.
62% of woodworking firms said they would spend less than $250,000 on capital investment over the next three years.[2] That is the highest share in the lowest bracket since the 2020 study. The reason is structural, not cyclical: 73.0% of U.S. wood kitchen cabinet establishments have fewer than 10 employees, compared with 58.1% across all U.S. manufacturing.[4] Millwork is a small-shop industry. It always has been, and the equipment market that serves it needs to reflect that.
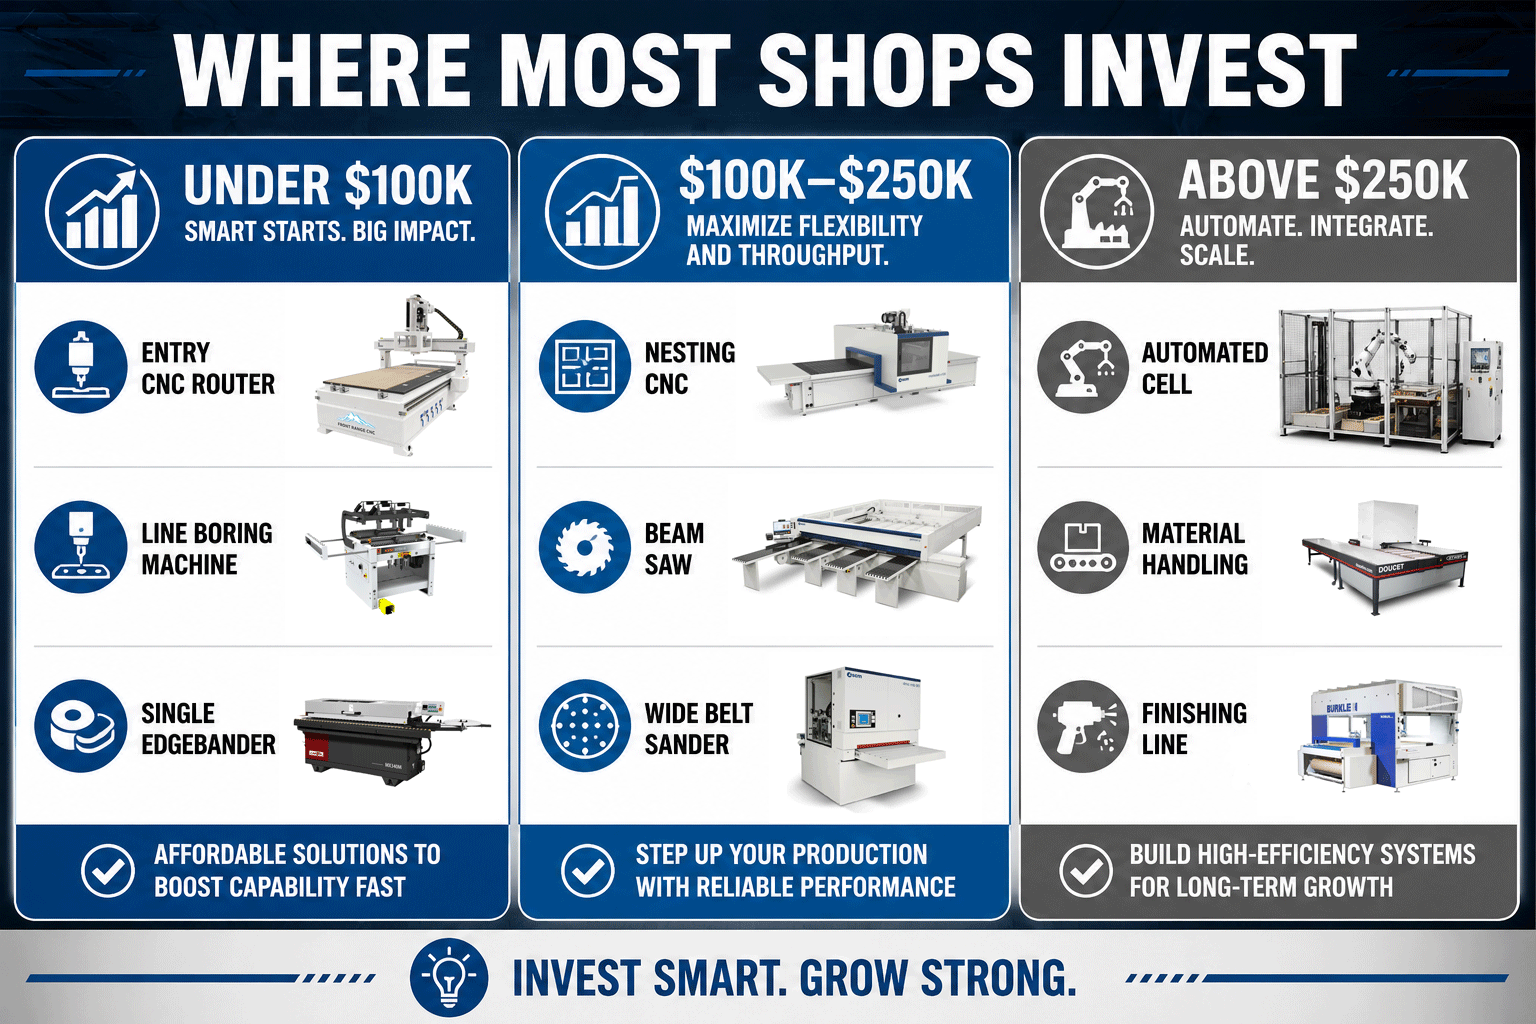
| Budget Range | Typical Equipment Scope |
|---|---|
| Under $100,000 | Entry-level CNC router, single-sided edgebander, line boring machine |
| $100,000–$250,000 | Nesting CNC, beam saw, mid-tier edgebander, wide belt sander |
| Above $250,000 | Work cells, automated material handling, finishing lines |
Made-to-Order Rebounded to 59%, and That Changes the ROI Math
59% of woodworking manufacturers said made-to-order production accounted for more than four-fifths of their product mix in 2026.[2] That is up from a low of 47% in 2023[2] and represents a meaningful shift in how ROI calculations work.
Made-to-order mix is the single best predictor of CNC payback. Batch-of-one production punishes setup time, every job is a new setup. When 80% of your work is custom, nesting software, parametric CAM, and automatic part labeling stop being upgrades. They become the only way to hold margin. Among woodworking shops that increased computerization, 67.6% did it in product design and 65.5% did it in machining.[5] Those are exactly the two functions batch-of-one production depends on most.
Browse nesting CNC routers built for high-mix, low-volume production environments.
Why Shops Invest in Automation, and Why Labor Is Not the Primary Driver
Almost every trade article claims shops buy CNC because they cannot find workers. The peer-reviewed data says otherwise.
A survey of 139 North American secondary woodworking manufacturers asked firms to rate the benefits driving their digitization investment. Improved productivity scored 4.6 out of 5. Product quality and process consistency tied at 4.4. Addressing labor shortages finished dead last at 3.5.[5] The same study then asked what blocks firms from increasing digitization. Skilled labor difficulty scored highest at 3.7, meaning labor is not why shops automate. Labor is why they cannot.
| Benefit Driving Automation Investment | Rating (out of 5) |
|---|---|
| Improved productivity | 4.6 |
| Product quality | 4.4 |
| Process consistency | 4.4 |
| Increased customization | 4.2 |
| Manufacturing flexibility | 4.1 |
| Shorter lead times | 4.0 |
| Raw material utilization | 3.8 |
| Addressing labor shortages | 3.5 |
The Labor Math: You Cannot Staff Your Way to Capacity
Woodworkers held 214,600 jobs in the United States in 2024. The Bureau of Labor Statistics projects employment will decline 2% to 211,100 by 2034, and names the cause directly: automation and the use of computer numerically controlled machines in wood product manufacturing.[6]
Even with employment falling, roughly 21,400 woodworker openings are expected each year through 2034. Every one of them comes from workers transferring to other occupations or leaving the labor force, none from industry growth.[6] Shops are not competing for new workers entering the trades. They are replacing the ones who leave.
The construction sector tightens the downstream picture further. The industry needs an estimated 349,000 net new workers in 2026 and 456,000 in 2027 just to keep labor supply and demand in balance.[7] One survey of 500 construction and trades professionals named carpenters and woodworkers the trade hardest hit by the skills shortage, with 39.4% pointing to quality of workmanship as the biggest impact.[8]
Employee training was the single top planned investment area for 2026, named by 39% of firms.[2] It beat every machinery category. Two years earlier, solid wood processing led at 37%.[3] By 2026 it sat at 27%, behind training, assembly, and sales.[2]
The post-purchase data explains the shift. Among firms that invested in computerized equipment, 62.7% sought formal training in machine operation.[5] Another 33.3% needed basic computing training, 32.0% needed advanced programming, and 29.3% needed maintenance and repair training.[5] Only 20.0% of investing firms sought no formal training at all.[5]
Presidential Proclamation 10976 took effect October 14, 2025. It imposed a 10% ad valorem tariff on softwood timber and lumber imports, 25% on certain upholstered wooden products, and 25% on completed kitchen cabinets, vanities, and parts thereof.[12]
Here is what most published coverage still gets wrong: a January 2026 amendment delayed the scheduled increases. The tariff on upholstered wooden products rises to 30% and the tariff on kitchen cabinets and vanities rises to 50% on January 1, 2027, not January 1, 2026.[13] Many trade articles still report the 50% cabinet tariff as already in force. It is not. Shops have until the end of 2026 to plan around it.
One additional flag worth watching: the Commerce Department has been directed to report to the President on hardwood timber and lumber imports by October 1, 2026, signaling that hardwood products may be next on the tariff schedule.[12] Shops sourcing imported hardwood or hardwood components should put that date on the calendar now.
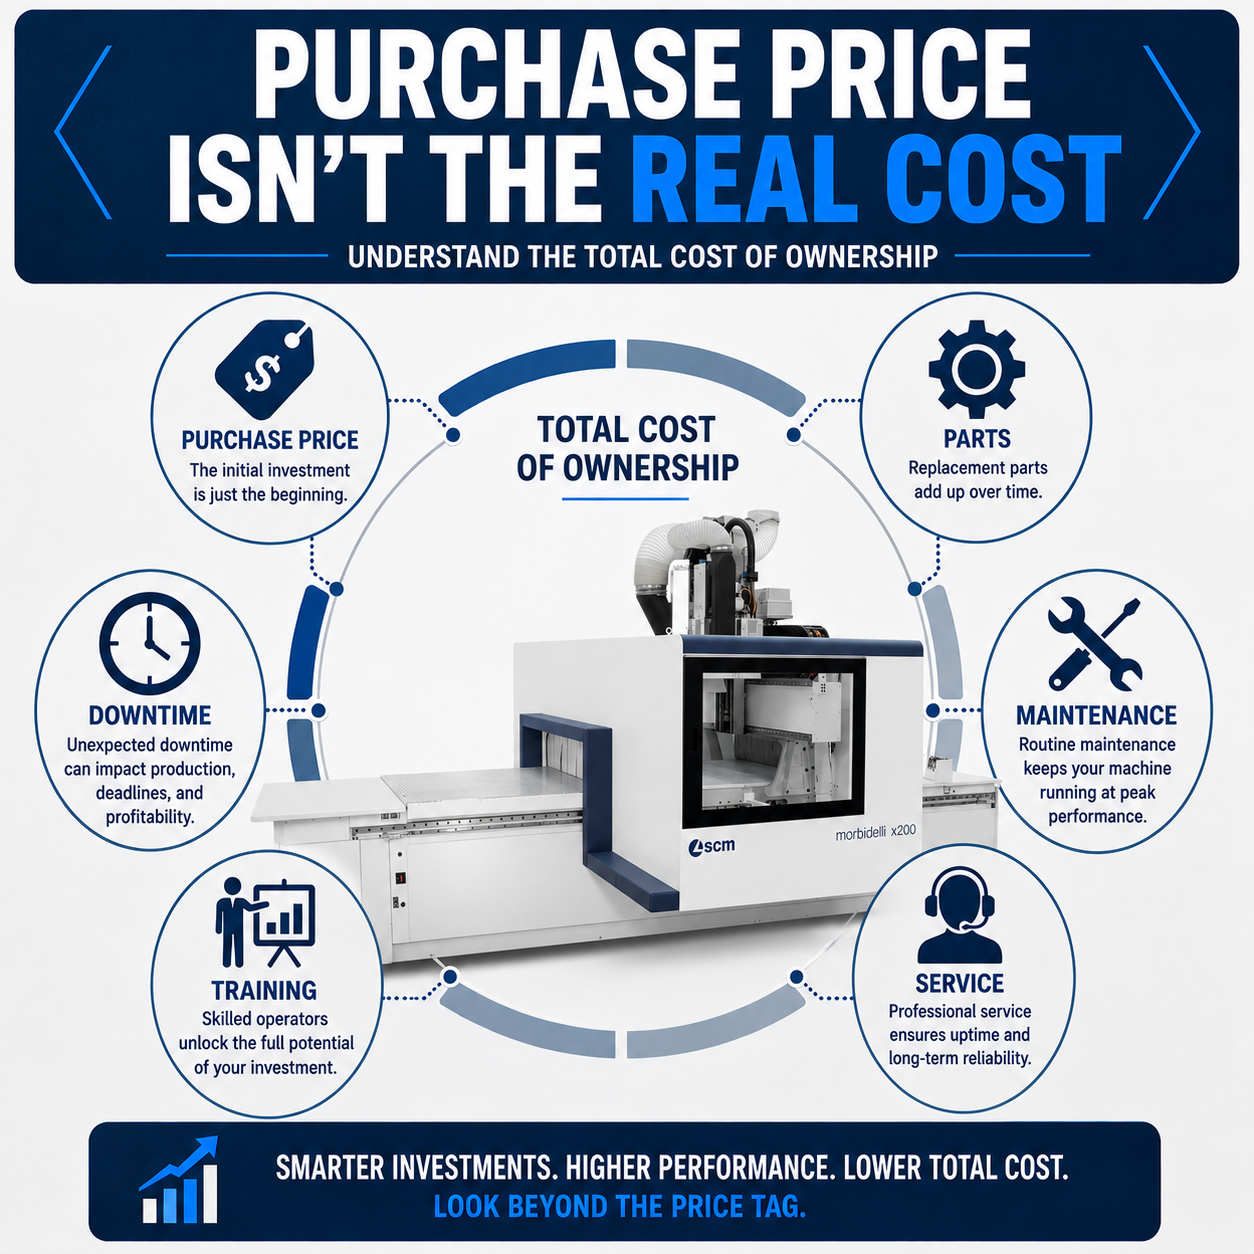
Woodworking machinery has never been more expensive. The Producer Price Index for sawmill and woodworking machinery reached 394.7 in May 2026, on a December 1980 base of 100, roughly four times the index's starting level.[14]
Parts run a steeper curve. The index for parts, attachments, and accessories stood at 167.7 in February 2026, on a June 2012 base of 100.[15] That is a 67.7% increase in consumable and replacement part costs in under 14 years. The purchase price is a down payment on the lifetime cost, and the down payment keeps getting larger while the ongoing cost compounds separately.
Service strategy follows the same logic. Among firms that invested in computerized equipment, 76.0% said a combination of in-house expertise and outsourcing was the best approach to repairs. Only 14.7% preferred to handle repairs entirely in-house.[5] Plan for a service partner before you need one, not after.
The core of high-mix production. Entry-level nesting machines under $100K pay back fastest in made-to-order shops running more than 80% custom work.
Browse CNC Machining CentersThe machine most often paired with a nesting CNC. Mid-tier edgebanders with EVA and PUR capability fit the $100K–$250K budget range where most 2026 buyers are operating.
Browse EdgebandersSurface quality before finishing. Calibration sanders paired with CNC nesting lines reduce finishing time and rework, two of the top drivers behind automation investment.
Browse Wide Belt SandersDust Collection: The Compliance Trend Nobody Puts in the Trend Reports
Dust collection carries more regulatory weight than any other equipment category in the shop, and it appears in almost no trend coverage.
OSHA's enforceable permissible exposure limit for wood dust is 15 mg/m³ total dust and 5 mg/m³ respirable fraction over an eight-hour time-weighted average.[18] NIOSH recommends 1 mg/m³ for all wood dust.[18] That is a 15-to-1 gap between the legal minimum and the health-protective recommendation, a gap that is worth understanding before the next equipment layout decision.
Species matter significantly. OSHA notes that dust from oak, mahogany, beech, walnut, birch, elm, and ash has been reported to cause nasal cancer in woodworkers.[18] Fire and explosion risk compounds the exposure concern. In 2018, wood and food products accounted for an average of 70% of materials involved in combustible dust fires and explosions.[19] The U.S. Chemical Safety Board identified 281 combustible dust incidents between 1980 and 2005, killing 119 workers, injuring 718, and damaging facilities across 44 states, with wood accounting for more than 20% of all explosions by material.[20]
| Compliance Target | Typical Equipment Tier Required |
|---|---|
| Meet OSHA PEL (15 mg/m³ total dust) | Single-stage collector, correctly sized ducting |
| Approach NIOSH REL (1 mg/m³) | Cyclone separation plus cartridge filtration |
| Combustible dust NEP readiness | Spark detection, explosion venting, engineered ducting, documented maintenance program |
Explore dust collection systems sized for every shop configuration, from single-machine setups to full production lines.
What to Watch Heading into 2027
Remodeling demand is the floor under most millwork work, and it is flattening. Harvard's Leading Indicator of Remodeling Activity projects homeowner improvement and repair spending to reach $518 billion by the end of 2026, with year-over-year growth easing from 2.1% at midyear to 1.6% by year-end.[22] By the first quarter of 2027, that growth is projected to slow to just 0.5% year over year, a pace below overall inflation.[23]
Three signposts worth tracking in the months ahead:
- The Commerce Department hardwood timber report, due to the President by October 1, 2026, the first signal on whether hardwood imports join the tariff schedule.[12]
- Remodeling permits, the leading input Harvard flags as the driver of the 2027 slowdown.[23]
- Mass timber adoption. Glulam beams, columns, and cross-laminated timber panels are being CNC-machined offsite from BIM-generated toolpath files and delivered just-in-time, the same BIM-to-CNC workflow that architectural millwork shops are beginning to adopt.[24]
The shops pulling ahead in 2026 are not the ones with the biggest budgets. They are the ones who kept investing when it was uncomfortable. Before finalizing the next purchase, three data-backed principles are worth internalizing:
- Build the case on productivity, not headcount. Shops rated improved productivity 4.6 out of 5 as the top driver of automation investment, with labor relief last at 3.5.[5] The internal business case that gets approved leads with parts per shift, rework rate, and setup time.
- Small shop, same payoff. Firms that invested in digitization rated their success at 6.7 out of 10 on average. Small firms reported 6.7. Large firms reported 6.8.[5] The "automation is for big shops" objection does not survive the actual numbers.
- Budget training and parts up front. 62.7% of firms needed formal machine operation training after investing,[5] and parts costs rose 67.7% in under 14 years.[15] Quote the machine, the training, and the first year of wear parts together, not the machine alone.
Contact a Würth Baer Machinery specialist about a machine and training package sized to your shop and your budget. Browse CNC machining centers, edgebanders, wide belt sanders, and dust collection systems, or request a consultation to discuss the right fit for your operation.
[1] U.S. Bureau of Labor Statistics, Industry Productivity Program. Sectoral Output for Manufacturing: Millwork (NAICS 32191), series IPUEN32191T300000000. FRED, Federal Reserve Bank of St. Louis. fred.stlouisfed.org
[2] Bumgardner, M., Buehlmann, U., and Koenig, K. 17th Annual Housing Market Study. Virginia Tech, USDA Forest Service Forest Products Laboratory, and Woodworking Network/FDMC, 2026. woodworkingnetwork.com
[3] Buehlmann, U., Bumgardner, M., and Koenig, K. 15th Annual Housing Market Study. Virginia Tech, USDA Forest Service, and Woodworking Network/FDMC, 2024. woodworkingnetwork.com
[4] U.S. Bureau of Labor Statistics. Quarterly Census of Employment and Wages, 2019 data, as cited in Bumgardner and Buehlmann, Forest Products Journal 72(1). vtechworks.lib.vt.edu
[5] Bumgardner, M. and Buehlmann, U. "A Preliminary Assessment of Industry 4.0 and Digitized Manufacturing in the North American Woodworking Industry." Forest Products Journal 72(1): 67–73, 2022. Survey of 139 North American secondary woodworking manufacturers. vtechworks.lib.vt.edu
[6] U.S. Bureau of Labor Statistics. Occupational Outlook Handbook: Woodworkers. 2024–2034 projections, last modified August 28, 2025. bls.gov
[7] Associated Builders and Contractors. 2026 Workforce Shortage Analysis. Reported via Construction Dive. constructiondive.com
[8] Eagle Woodworking. Survey: Woodworking Hardest Hit by the Skills Shortage. Vendor-commissioned survey of 500 U.S. construction and trades professionals, 2026. Methodology not fully published. eaglewoodworking.com
[12] Proclamation 10976 of September 29, 2025: Adjusting Imports of Timber, Lumber, and Their Derivative Products Into the United States. Federal Register Vol. 90, No. 191, pp. 48127–48132. govinfo.gov
[13] Amendments to Adjusting Imports of Timber, Lumber, and Their Derivative Products Into the United States. Federal Register Vol. 91, No. 6, January 9, 2026. govinfo.gov
[14] U.S. Bureau of Labor Statistics. Producer Price Index by Industry: Sawmill and Woodworking Machinery, series PCU333243333243A. May 2026 observation. fred.stlouisfed.org
[15] U.S. Bureau of Labor Statistics. Producer Price Index by Industry: Parts, Attachments and Accessories for Sawmill and Woodworking Machinery, series PCU333243333243A4. February 2026 observation. fred.stlouisfed.org
[18] U.S. Occupational Safety and Health Administration. Woodworking eTool, Production: Wood Dust. Current standard, 29 CFR 1910.1000 Table Z-1. osha.gov
[19] U.S. Occupational Safety and Health Administration. Directive CPL 03-00-008: Revised Combustible Dust National Emphasis Program. 2023, citing 2018 incident data. osha.gov
[20] U.S. Chemical Safety and Hazard Investigation Board. Investigation Report: Combustible Dust Hazard Study. 2006, covering 1980–2005. csb.gov
[22] Joint Center for Housing Studies of Harvard University. Leading Indicator of Remodeling Activity: Remodeling Growth Set to Downshift in Late 2026. April 2026. jchs.harvard.edu
[23] Joint Center for Housing Studies of Harvard University. Leading Indicator of Remodeling Activity: Remodeling Growth to Slow Sharply in Early 2027. 2026. jchs.harvard.edu
[24] Coelho, R. V., Anderson, A. K., and Tommelein, I. D. "Investigation of the Supply Chain of Mass Timber Systems." IGLC31, Lille, France, 2023. iglcstorage.blob.core.windows.net
 CNC Machining Centers
 Edgebanders
 Dust Collectors
 Wide Belt Sanders
 SCM
 Cantek
